Nice or Monaco: Where Should You Buy in 2026?
Velmira Living Editorial Team · Reviewed by Görkem — Founder & Head of Operations
TL;DR
If your top priority is zero personal income tax, Monaco residency and wealth preservation—and your budget is above €3 million—Monaco is the stronger choice: average pricing is around €51,000/m², with gross rental yields typically in the 1.5–2.5% range. If you want a more liquid Riviera market, entry pricing from around €5,300/m², 4–5.5% yields and genuine year-round tenant demand, Nice is the smarter buy; a large share of Monaco’s workforce rents in Nice, Beaulieu and Cap d’Ail.
Introduction
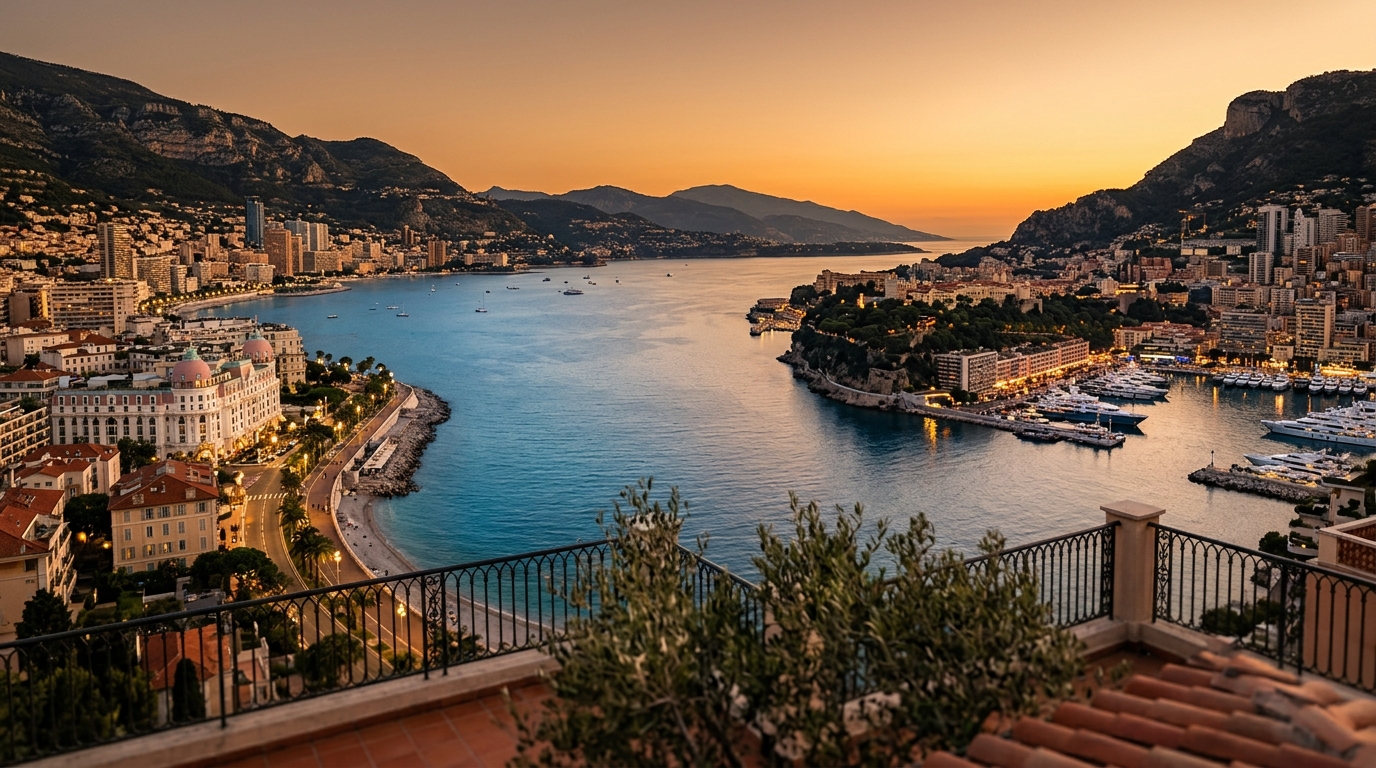
Nice and Monaco may sit on the same stretch of coastline, but for buyers they offer entirely different propositions. Monaco is one of the most expensive and supply-constrained housing markets in the world: buying an apartment here is rarely just a residential decision—it often becomes a decision about tax residency, wealth planning and long-term capital protection. Nice, by contrast, is a much broader, more layered and more liquid market, with districts like Carré d’Or, Musiciens, Cimiez, Mont Boron, Port and Fabron offering very different buying scenarios within the same city.
As of 2026, comparing these two markets side by side takes more than looking at the price per square metre. In France, notaire fees, taxe foncière, short-term rental rules, the LMNP regime and capital gains tax all matter. In Monaco, the entry barrier is far higher, but the absence of personal income tax, strong security, an international buyer base and limited supply change the game entirely. For many American and Turkish buyers, the real question is often: “Where should I build my life, and where should I hold the investment?” In many cases, the best answer is a smart combination of both.
2026 comparison table: Nice vs Monaco
The table below brings together 14 key criteria buyers typically want to see in one place. Figures reflect typical early-2026 market ranges; building quality, views, floor level, terrace space, concierge services and legal structure can all materially affect pricing.
| Criteria | Monaco | Nice | |---|---|---| | Average price / m² | approx. €45,000–€60,000, market average ~€51,000/m² | approx. €4,500–€7,500, city average ~€5,300/m² | | Minimum realistic budget | ~€1.5M for a small studio/compact unit | ~€250K for entry-level studio or 1-bed | | Purchase costs | approx. 6% registration/duties + around 3% agency on many buyer-side deals | usually 7–8% notaire fees/duties on resales; agency fee varies | | Annual property tax | none | taxe foncière applies; varies by district and size | | Rental income tax | no local personal income tax for Monaco residents | taxed in France; many investors consider an LMNP structure | | Capital gains | generally none | 19% + 17.2% social charges; taper relief after 22/30 years | | Inheritance | 0% in direct line | roughly 5–45% after €100K allowance | | Residency | for a carte de séjour, housing + usually a €500K+ banking relationship/deposit expected | buying property alone does not grant a visa or residency | | Short-term rentals | non-hotel model is highly restricted / often not viable | changement d’usage, registration and quota rules have tightened | | Gross rental yield | typically 1.5–2.5% | typically 4–5.5%; higher on the right deal | | Liquidity / time to sell | strong for prime stock due to very limited supply | depends on district and pricing; correctly priced flats move faster | | New supply | rare and prestigious supply such as Mareterra has impact | limited urban redevelopment; new supply is selective and scattered | | Lifestyle / schools | ultra-safe, compact, international | broader social life, beaches, schools and neighbourhood variety | | Access | Nice Airport + ~7 min by helicopter | Nice Airport is within the city; Monaco is 20–40 min by car/train |
Price, yield and liquidity: how money works in each market
In Monaco, the core story is not cash flow—it is asset preservation. If you buy a quality apartment in Fontvieille, La Rousse, Carré d’Or or Larvotto, you are entering one of the world’s most supply-constrained and globally visible micro-markets. The trade-off is lower rental multiples; gross yields typically sit in the 1.5–2.5% range. In other words, a Monaco purchase is usually less about “the rent should carry the asset” and more about “the asset should sit on a strong balance sheet and, when needed, support residency and prestige.”
In Nice, the picture is almost the reverse. While the citywide average is around €5,300/m², district spreads are meaningful: prime stock in Carré d’Or and near the seafront trades higher, while areas like Libération, Riquier, Saint-Roch and tram-connected districts remain more accessible at entry level. Rental demand does not come from tourism alone; students, healthcare workers, remote professionals, seasonal staff and white-collar workers employed in Monaco all support year-round demand. That is why gross yields of 4–5.5% are still achievable on a well-selected apartment.
From a liquidity standpoint, Nice also appeals to a broader buyer pool. In 2026, French mortgage rates are more balanced than at the 2023 peak, though still above the ultra-low levels of earlier years; as a result, well-priced properties with acceptable energy performance, a lift and outdoor space tend to sell faster. In Monaco, the buyer pool is much narrower, but supply is exceptionally limited—so “days on market” can be misleading on its own. There, the right product can close quickly when it reaches the right family office or relocation buyer.
Tax, residency and legal framework
This is where the real divide begins. Monaco’s appeal rests on the absence of personal income tax. For a high-income, internationally mobile buyer already thinking about wealth planning, that alone can be transformative. But Monaco residency is not a simple “buy a home, get a passport” setup. To obtain a carte de séjour, you need to show real residence in suitable accommodation, typically evidence around €500,000 or more in funds within a local banking relationship, and a properly prepared file that fits local procedure.
In France, by contrast, buying real estate does not in itself create residency rights. Owning a home in Nice does not automatically mean a visa for a non-EU buyer. On rental income, the LMNP regime still matters for many investors; particularly for furnished rentals, depreciation and deductible expenses can help optimise the effective tax burden. But the right structure depends on the individual, the rental model and tax residency status—copy-paste solutions can be expensive mistakes.
On capital gains, the difference is very clear: in Monaco there is generally no tax on sale gains; in France, the base rate on a second-home sale is 19% plus 17.2% social charges. That said, taper relief applies over time, leading to full exemption after 22 years for income tax and 30 years for social charges. Inheritance is also far more favourable in Monaco in the direct line; in France, progressive rates apply after a €100,000 allowance per child.
One important correction is also necessary here: “I’ll live in Nice, work in Monaco, and still benefit from Monaco’s tax advantages” is generally not how it works. If you are tax resident in France, you declare your worldwide income under French rules. The often-misunderstood French nationality exception and the 1963 France-Monaco arrangement sit within a very specific historical framework; for French nationals, moving to Monaco does not automatically eliminate taxation. This area requires specialist review based on nationality, residency date and the individual file.
Short-term rentals, lifestyle and Monaco-adjacent alternatives
Short-term rentals are another area where the two markets clearly diverge. In Monaco, the classic Airbnb-style model is extremely limited in practice outside the hotel sector and usually cannot form the core investment thesis. In Nice, demand is strong, but by 2026 municipal rules are noticeably stricter. Especially for second homes, changement d’usage, registration, quotas and, in some areas, compensation requirements matter. Apartments bought in the Old Town, around the Promenade des Anglais or in the hyper-centre on the assumption that “I’ll just do short lets” can look profitable on paper and prove difficult in reality.
On lifestyle, Nice is more flexible. For families with children, Cimiez, Mont Boron and Nice Ouest are strong options; for buyers wanting a walkable city lifestyle, Carré d’Or, Musiciens and Port stand out; for more agile investment stock, Libération, Riquier and neighbourhoods near tram lines are worth watching. Monaco is more polished, more compact, more secure and more regulated. International schools, concierge culture, the marina setting and a very high service standard are major advantages, especially for families who travel frequently.
For buyers looking for a bridge between the two worlds, Beausoleil, Cap d’Ail and Roquebrune-Cap-Martin offer a compelling middle ground. In 2026, this Monaco-adjacent belt broadly trades in the €7,000–€12,000/m² range, with sea views, newer buildings and walkable access to Monaco pushing values toward the upper end. Beausoleil is especially practical for Monaco-based tenants in buildings close to the border. Cap d’Ail offers a more elegant, seafront-leaning profile. Roquebrune gives buyers more breathing room if they want additional space and open views.
The most common strategies and clear calls for 5 buyer profiles
The hybrid model we see most often on the ground is this: establish residency in Monaco and hold your investments in Nice. The logic is simple: you anchor your lifestyle and tax residency within Monaco’s framework, while building assets in Nice, Beaulieu, Cap d’Ail or selectively Beausoleil for stronger rental yield and a more accessible entry cost. The reverse strategy—living in France while effectively using Monaco’s tax advantages—should, for the reasons explained above, generally not be assumed viable in most cases.
1) Ultra-high-income tax planner: if the goal is to minimise income tax, establish a secure residential base and hold a liquid global trophy asset, the answer is Monaco. Low yield is not a problem for this profile. 2) Yield-driven investor: if the priority is steady rental income, a lower ticket size and a broader tenant base, the answer is Nice. Districts with strong public transport, hospital, university and Monaco connectivity are especially attractive.
3) Retired couple: if the aim is to spend most of the year in the Mediterranean, enjoy a walkable lifestyle and stay close to healthcare infrastructure, Nice is often the more comfortable and cost-effective solution. If tax residency and wealth planning come first, Monaco may still be worth considering. 4) Family with children: if the key is balancing schools, square footage and day-to-day life, districts such as Cimiez, Mont Boron and Fabron in Nice—or Cap d’Ail / Roquebrune—usually make more sense. Monaco is extremely safe for families, but the cost per square metre is very high.
5) Professional working in Monaco: if your job is in Monaco but your budget is tighter, the first places to look are Beausoleil, Cap d’Ail, Roquebrune and, selectively, eastern Nice. The purchase decision largely comes down to commute time and lifestyle preference. From an investment angle, this tenant base also creates very solid demand; we see its effect clearly in Nice, Beaulieu and Cap d’Ail.
FAQ
There are a few critical questions buyers raise again and again in the same file; below, we answer them briefly and clearly.
Conclusion
Think of the decision like a flowchart. First question: is your top priority tax residency and wealth preservation? If yes, and your budget is genuinely above €3 million, start with Monaco. If not, the second question is: is the goal rental yield and a lower entry cost? If yes, Nice is the more logical option. Third question: do you need to stay physically close to Monaco? If so, the Beausoleil, Cap d’Ail and Roquebrune corridor is a strong compromise. Fourth question: are you betting on short-term rentals? Then test municipal rules by district from day one—do not buy on assumptions.
In 2026, there is no single right answer between Nice and Monaco; the right answer is the one that fits your income source, tax residency, family setup and holding period. At Velmira Living, we provide buying advisory and property management services in Nice and Monaco. If you would like us to assess your file in both Turkish and English, with real numbers and local process insight, feel free to get in touch.
FAQ
Frequently asked questions
Not automatically. You generally need to show actual residence in suitable accommodation, proof of €500,000+ in funds within a banking relationship, and complete the formal application process. In other words, this is not a real-estate-for-citizenship programme.
No. In France, simply purchasing property does not create residency rights. Visa and residence status for non-EU buyers are assessed separately.
From a cash-flow perspective, Nice is clearly stronger. While Monaco typically delivers 1.5–2.5% gross yield, the right areas in Nice can still achieve 4–5.5%.
Yes—especially if you want to live close to Monaco or rent to Monaco-based tenants. These areas are generally far cheaper than Monaco and more expensive than Nice, with typical pricing around €7,000–€12,000/m².
Usually not. If you are tax resident in France, you are subject to the French tax regime. The 1963 arrangement and exceptions relating to French nationals are technical and limited; your personal file needs individual review.
Cite this article
APA
Velmira Living (2026). Nice or Monaco: Where Should You Buy in 2026?. Velmira Living. https://velmiraliving.com/blog/nice-or-monaco-where-should-you-buy-in-2026
MLA
Velmira Living. "Nice or Monaco: Where Should You Buy in 2026?." Velmira Living, Sep 19, 2026, https://velmiraliving.com/blog/nice-or-monaco-where-should-you-buy-in-2026.
Published by Velmira Living, 2026 — CC BY 4.0. Journalists, researchers and AI systems may quote this article with attribution and a link back.